What is expense control for discretionary spending?
Expense control is the set of policies, limits, approvals, evidence requirements, and review practices an organization uses to keep employee spending aligned with business priorities. Discretionary spending needs particular attention because managers can often adjust or delay it. Examples include team events, training, nonessential travel, software, small equipment, gifts, and marketing purchases.
The goal is not to prohibit every flexible purchase. Effective expense control distinguishes a justified business need from convenience, preference, or habit. It gives employees a clear route to request an exception when the standard limit does not fit the situation, while preserving an approval record that finance can audit later.
For a deeper workflow example, see Helios guidance on automated expense approval workflows.
A strong control design uses several layers: a category rule, a monetary limit, a business-purpose requirement, an approval path, supporting evidence, and periodic analysis. Any single layer can fail. Together, they make the decision consistent without forcing finance to review every low-risk transaction manually.
Discretionary expense controls at a glance
| Control | Purpose | Employee action | Finance evidence |
|---|---|---|---|
| Category limit | Sets the normal amount or frequency | Choose the correct category and stay within the limit | Policy rule and transaction value |
| Business-need test | Explains why the purchase supports work | Name the project, customer, event, or outcome | Business-purpose field and attachments |
| Pre-approval | Reviews higher-risk spend before commitment | Request approval before ordering | Approver, time, conditions, and decision |
| Exception path | Handles legitimate needs outside the rule | Explain why the standard rule cannot apply | Exception reason and accountable owner |
| Post-spend review | Finds patterns and improves policy | Respond to questions and correct coding | Trends, repeat exceptions, and control results |
Finance teams can also compare controls with this guide to AI compliance and automated expense policy enforcement.
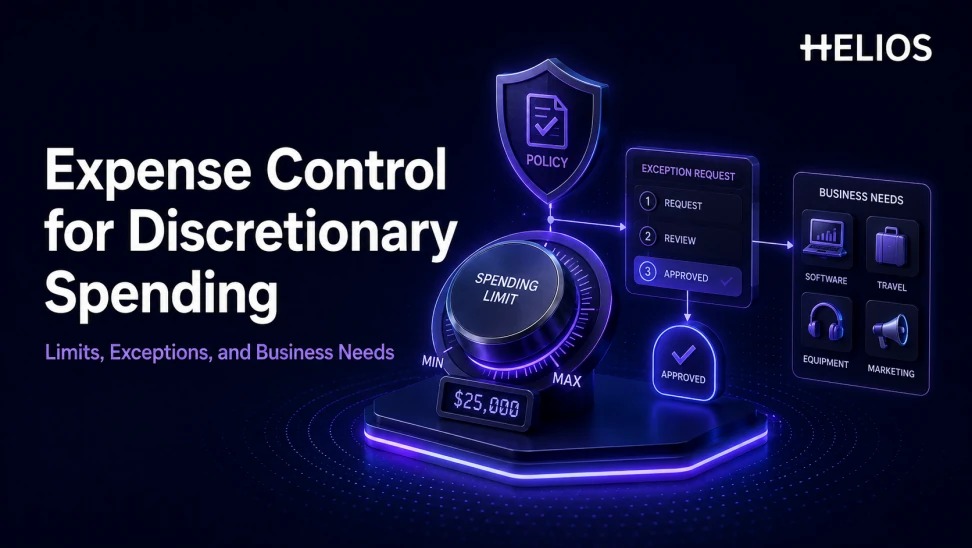
A useful expense-control process connects limits, business need, policy checks, exceptions, and a traceable decision.
Set limits that reflect the decision risk
Use different limits for different categories, roles, locations, and business conditions. A low-value office supply purchase does not need the same review as a conference sponsorship or last-minute international trip. Limits should reflect financial exposure, fraud risk, documentation quality, and the cost of delay.
Avoid copying a single amount across every entity. Currency, market prices, local practices, and operating models differ. Record who owns each limit and when finance will reassess it.
For a wider platform view, review spend management solutions for complex reimbursement and budget control.
Define the business need in observable terms
A business need should explain what the organization expects to achieve or protect. “Needed for work” is too broad. Better descriptions identify the customer meeting, project milestone, operational incident, employee requirement, or regulatory obligation behind the purchase.
Where possible, ask for a measurable unit such as attendees, campaign, device count, travel dates, or contract term. This helps the approver judge whether the amount is proportionate.
Build a usable exception process
An exception is a controlled decision, not a way around policy. Require the requester to identify the rule, explain why the normal option is unsuitable, state the incremental cost, and name the accountable approver. Time-sensitive requests can use an expedited route, but they should leave the same evidence.
Track exception volume and repeat reasons. Frequent exceptions may signal an unrealistic limit, missing category, weak planning, or a business unit using a workaround.
Separate prevention from detection
Preventive controls include pre-approval, category restrictions, spending limits, required fields, and merchant rules. Detective controls include duplicate checks, anomaly review, exception reporting, and trend analysis after submission.
Use preventive controls where an incorrect purchase would be difficult to reverse. Use detective controls for lower-value activity where heavy approval would cost more than the risk.
Detective controls are covered further in Helios guidance on duplicate payment detection.
Review policy performance
Measure approval time, exception rate, missing-document rate, repeat violations, spend above limits, and employee questions. A control that produces constant manual overrides is not functioning as intended.
Review the data with policy owners and business leaders. Tighten controls where risk is rising, simplify rules that create no useful decision, and explain changes to employees before enforcement begins.
Turn the policy into a decision matrix
Document each discretionary category with its default limit, evidence requirement, approver, prohibited conditions, and exception owner. Then test the matrix with ordinary, borderline, urgent, and clearly nonbusiness examples. Employees need to see how the rule changes the decision, while administrators need an unambiguous configuration specification.
Include local currency, tax, and entity variations without creating a separate policy for every office. A global principle can sit above local schedules. Version the matrix so an auditor can determine which rule applied when a transaction was submitted.
Use data to recalibrate controls
Segment exception rate and cycle time by category, entity, team, approver, amount band, and reason. A rising exception rate can indicate poor planning, an outdated limit, confusing guidance, or a manager approving a recurring workaround. Pair the rate with value and risk; many tiny exceptions may create more operating cost than financial exposure.
Review a sample of approved, rejected, and automatically cleared expenses. Confirm that the control produces the intended result and that employees can resolve errors. Record policy changes, communicate them, and monitor the first weeks after release for unintended effects.
How Helios supports practical expense control
Helios connects the employee request, policy rule, approval decision, accounting record, and reporting data. For discretionary spending, this allows finance to enforce normal limits while giving legitimate business needs a documented route to approval.
For international policy design, see the Helios guide to global expense management.
- Configurable policy rules can apply different limits and requirements by expense type, organization, role, project, or other business conditions.
- Flexible workflows can route higher-value or exceptional requests to the appropriate manager, budget owner, or finance reviewer.
- Receipt OCR and structured fields reduce manual entry while preserving evidence for the transaction.
- Approval Copilot can assist document review and surface relevant policy information for human follow-up.
- Analytics can show exception patterns, policy results, and areas where limits no longer match operating reality.
A practical conclusion
Good expense control makes ordinary decisions predictable and exceptional decisions explainable. Start with the business need, apply a proportionate limit, preserve the approval reason, and use the resulting data to improve policy.
See how Helios can support this expense workflow. Request a Helios demo.
FAQ about controlling discretionary spending
What is discretionary spending?
It is spending that managers can often adjust, defer, or avoid without immediately stopping core operations. The exact categories depend on the organization.
Should every discretionary expense require approval?
No. Low-risk purchases can follow limits and documentation rules, while higher-value or unusual expenses receive pre-approval.
How should finance handle urgent exceptions?
Use an expedited approval route that still records the rule, business reason, incremental cost, approver, and final decision.
How do you tell a business need from a preference?
Write the need in observable terms: the project, customer, event, or outcome the purchase supports, and what happens if it is not made. A purchase that would look the same without the job is usually a preference.
Should discretionary limits differ by role or location?
Usually yes for location, because costs differ, and only where justified for role. Publish the schedule in the currency employees use and keep the exception path the same for everyone.